Crypto and International Property
Crypto investors are increasingly using digital assets like Bitcoin and stablecoins to purchase international property, seeking currency diversification and residency through Golden Visa programs, a strategy which demands careful navigation of cross-borde
This article was produced with AI assistance and reviewed for accuracy.
Content is for informational purposes only and does not constitute financial advice.
Dubai Crypto Acceptance
Multiple developers accept Bitcoin and USDT
Portugal Crypto Buyers
Growing market of crypto wealth seeking property
Turkey Crypto Usage
High adoption — AML rules apply to property purchases
Tokenised Real Estate
RealT, Lofty — fractional ownership platforms emerging
ATO CGT Trigger
Using crypto to buy property is a disposal event
Crypto Mortgage
Nexo and similar — collateralised loans without selling BTC
Crypto and International Property: The New Frontier for Sovereign Wealth
AUSTRAC Reporting
Australian exchanges must report all fund transfers of any value and physical cash transactions of AUD $10,000 or more to the financial intelligence agency.
UAE Property Market
In Q1 2023, Dubai registered over 3,600 real estate transactions valued above $1.36 billion from buyers using crypto assets as a source of funds.
Portugal's Tax Shift
From January 1, 2023, Portugal introduced a 28% tax on crypto gains held for less than one year, ending its status as a zero-tax haven for individuals.
Settlement Speed
A USDC stablecoin transfer finalises on-chain in seconds to minutes, whereas a traditional international SWIFT wire transfer can take 2-5 business days.
Golden Visa Thresholds
Residency-by-investment programs often start at €250,000 (approx. AUD $415,000) for real estate, with higher tiers for direct citizenship pathways.
ATO Global Reach
The ATO automatically receives financial account data from over 100 jurisdictions under the Common Reporting Standard (CRS), increasing its visibility of offshore assets.
The convergence of cryptocurrency and international real estate is more than a niche trend; it represents a significant evolution in wealth management strategy. For a certain class of investor—one valuing autonomy, inflation resistance, and global mobility—these two asset classes form a powerful combination. They offer parallel paths to diversifying away from a single fiat currency and its associated domestic banking system, a strategy with particular resonance for Australians watching currency fluctuations and domestic property market cycles.
This entry explores the strategic rationale, practical mechanics, and regulatory complexities of using digital assets to acquire international property. We will cover everything from the efficiency of stablecoins in cross-border transactions to the intricate tax obligations that follow such an investment, providing a framework for the globally-minded crypto investor.
The Sovereign Investor's Rationale
The appeal of holding both crypto and foreign property stems from a shared philosophy of wealth sovereignty. Both assets exist, to varying degrees, outside the direct control of any single government or financial institution. Bitcoin, as a decentralised digital asset, offers a hedge against currency debasement and censorship. International property provides a tangible, yield-generating asset in a different legal and economic jurisdiction.
For an Australian investor, this dual approach offers a multi-layered diversification strategy. It mitigates exposure to the Australian dollar, the local banking sector's policies, and the domestic real estate market's specific risks. It is a modern interpretation of the age-old advice to not keep all one's eggs in one basket, updated for a digital and borderless age.
The mindset is one of radical self-reliance and jurisdictional arbitrage. An investor can hold Bitcoin on a Ledger device, secure it with a NordVPN for online privacy, and use the gains to acquire a tangible asset in a country with favourable tax laws or lifestyle benefits. It's about creating a personal balance sheet that is resilient to localised economic or political shocks.
Crypto as a Vehicle for Cross-Border Wealth Transfer
One of the most direct applications of crypto in this context is as a medium for moving significant capital across borders. The traditional method—a series of international wire transfers via the SWIFT network—is often slow, expensive, and burdened by opaque correspondent banking fees and stringent capital controls in some countries.
Digital assets offer a more efficient alternative. The process typically involves an investor selling a volatile crypto asset like Bitcoin or Ethereum for a stablecoin like USDC on an exchange such as Coinbase. This stablecoin, pegged 1:1 to the US dollar, can then be transferred to a wallet or an exchange in the destination country in minutes for a nominal network fee. Once there, it can be converted into the local fiat currency (e.g., Euros, Dirhams) to fund the property purchase.
However, this efficiency does not mean a lack of regulatory oversight. In Australia, the Australian Transaction Reports and Analysis Centre (AUSTRAC) requires digital currency exchange providers to report all transactions involving fund transfers, regardless of amount. This data is part of a global information-sharing framework, ensuring tax authorities like the ATO have visibility over capital movements.
Critical Insight: The primary advantage of using stablecoins for large transfers is not secrecy, but efficiency. It drastically reduces settlement time from days to minutes and can lower foreign exchange costs from 1-3% with banks to under 0.5% through crypto platforms. The regulatory trail remains; the financial plumbing is simply upgraded.
Golden Visas and the Crypto-Wealthy
Several countries have recognised the rise of crypto-generated wealth and have positioned their residency-by-investment programs, or 'Golden Visas', to attract these investors. These programs offer residency rights—and sometimes a path to citizenship—in exchange for a significant investment, often in real estate.
Jurisdictions actively courting crypto investors include:
- Portugal: While its crypto tax advantages have been curtailed, Portugal's Golden Visa remains popular. It traditionally required a real estate purchase of €280,000-€500,000, though recent October 2023 changes have shifted focus towards investment funds. Authorities have shown a willingness to accept proof of funds originating from crypto assets, provided a clear audit trail exists.
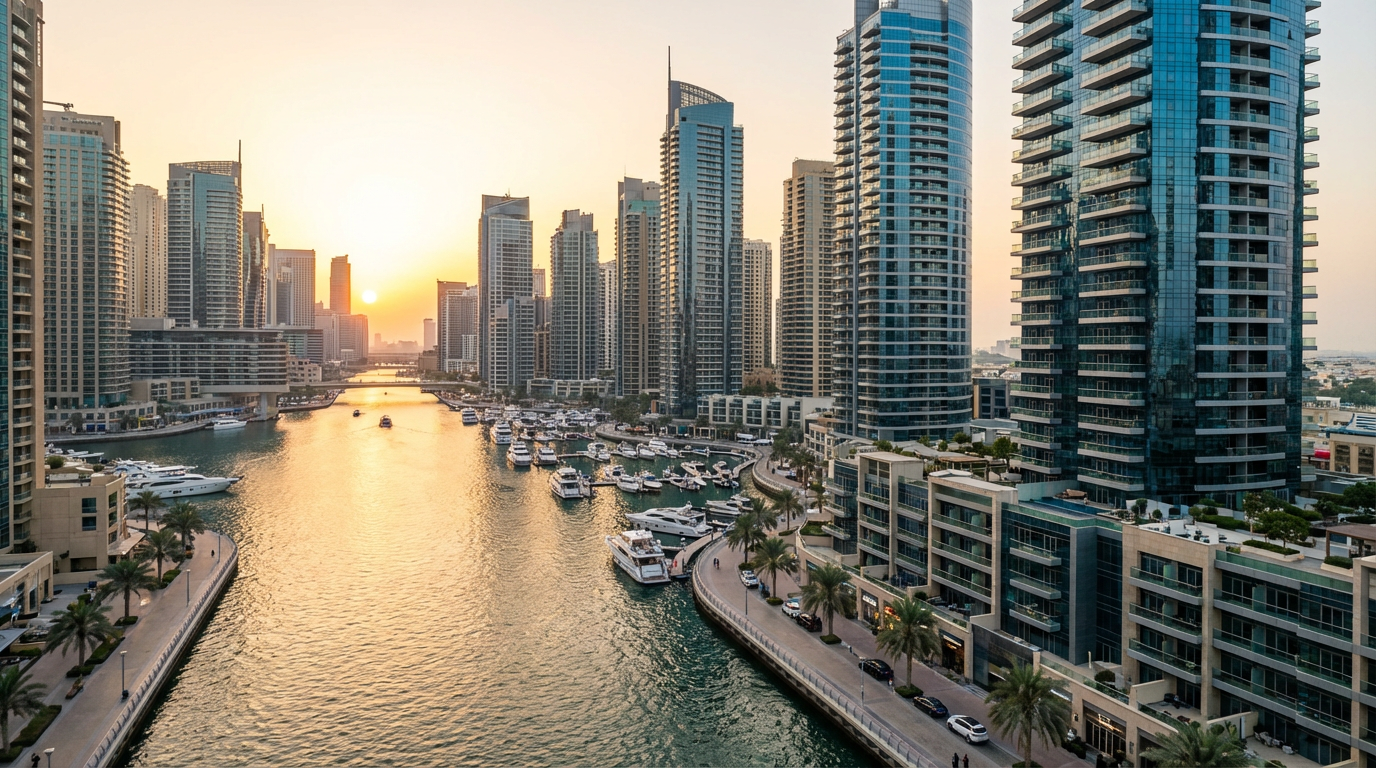
- United Arab Emirates (UAE): Dubai, in particular, has leaned into crypto. Multiple major property developers, including DAMAC Properties and Nakheel, accept crypto for payments. The UAE's Golden Visa can be obtained with a real estate investment of AED 2 million (approx. AUD $820,000), offering a 10-year renewable residency in a zero-income-tax jurisdiction.
- Malta: Known as the 'Blockchain Island', Malta offers residency and citizenship pathways for substantial investors. While direct property purchases are an option, the programs often require a combination of real estate investment, government contributions, and philanthropic donations, with total outlays often exceeding €700,000.
- Thailand: The Thailand Elite Visa program, while not a direct property-for-residency scheme, offers long-term visas for a flat fee. The country's regulated crypto exchanges and growing acceptance make it a popular destination for crypto nomads looking to establish a base in Southeast Asia.
Increasingly, developers in these regions are exploring asset tokenisation to fractionalise property ownership, a concept that sits at the intersection of DeFi and real estate. Learn More about how this technology works.
| Jurisdiction | Typical Minimum Investment (Real Estate) | Crypto Acceptance | Key Benefit |
|---|---|---|---|
| UAE (Dubai) | AED 2 Million (~AUD $820,000) | High (Developers & Exchanges) | 10-year residency, 0% personal income tax |
| Portugal | €500,000 (Investment Fund Focus Post-2023) | Moderate (Requires clear fund trail) | EU residency, path to citizenship |
| Malta | €700,000+ (Combined investment) | Moderate (Regulated framework) | EU citizenship by investment pathway |
| Thailand | N/A (Visa Fee Based) | Growing (Regulated exchanges) | Long-term (5-20 year) residency visa |
The Complex Tax Web for Australian Investors
Combining crypto gains and international property creates a multifaceted tax situation that requires careful management. For an Australian tax resident, global income and assets are assessable by the Australian Taxation Office (ATO). This principle is the foundation of the tax complexity.
Failing to understand the tax implications is the single biggest mistake an Australian crypto investor can make when buying property abroad. The ATO's data-matching capabilities, enhanced by agreements like the Common Reporting Standard, are extensive. Assuming offshore activities go unnoticed is a fiscally dangerous assumption.
Here are the primary tax events to consider:
- Crypto Disposal: The first taxable event occurs in Australia. When you sell cryptocurrency (e.g., BTC for AUD or USDC) to fund the property purchase, you trigger a Capital Gains Tax (CGT) event. The profit is calculated as the capital proceeds minus your cost base. If the crypto was held for over 12 months, you may be eligible for the 50% CGT discount. Using a service like Koinly is essential for calculating this accurately.
- Foreign Rental Income: Any rental income generated by your international property must be declared on your Australian tax return. You can typically claim a foreign income tax offset for any tax already paid on that income in the foreign country, preventing double taxation.
- CGT on the Foreign Property: When you eventually sell the international property, it is also subject to Australian CGT. The cost base includes the purchase price and other capital costs, and the capital proceeds are the sale price. Currency fluctuations between the AUD and the property's local currency can significantly impact the final capital gain or loss.
Professional advice is not optional. You will likely need tax advisors in both Australia and the property's host country to ensure compliance. For global property investment analysis and golden visa guides, see World Property Forum →
Stablecoins: The Settlement Layer for Global Real Estate
Stablecoins, particularly fully-reserved, audited ones like Circle's USDC, are becoming the preferred settlement instrument for these transactions. Their value proposition is clear: they combine the speed and low cost of digital assets with the price stability of a major fiat currency like the US dollar.
Consider the cost difference. A traditional bank wire for $500,000 AUD might incur a flat fee plus a foreign exchange spread of 1-2% ($5,000-$10,000). A USDC transfer involves converting AUD to USDC on an exchange like Binance for a fee often under 0.5%, paying a small on-chain transaction fee, and then converting USDC to local fiat on the other end. The total cost can be dramatically lower.
Every stablecoin carries an implicit trust assumption. With USDC, the user trusts that Circle holds 1:1 liquid reserves for every token issued and that the underlying banking partners are solvent. While highly reliable to date, this is a form of counterparty risk that does not exist with a truly decentralised asset like Bitcoin.
This risk is why due diligence is key. Transactions should be conducted with reputable, regulated entities. For property developments advertising "crypto accepted," it's vital to confirm if they are working with a registered digital asset firm to handle the conversion and custody, ensuring funds are properly managed and legally documented.
Case Study Insight: Using an Over-The-Counter (OTC) desk can be more efficient for very large transactions (>$250,000). An OTC desk provides a single, fixed price for the entire crypto-to-fiat conversion, removing the risk of price slippage that can occur on public exchange order books.
Case Study: An Australian Buys Property in Dubai
Let's walk through a hypothetical scenario. Alex, an Australian tax resident, made substantial gains from an early investment in Ethereum (ETH). They decide to diversify by purchasing an apartment in Dubai to gain a foothold in a tax-friendly jurisdiction and hedge against the AUD.
Step 1: Capital Realisation & Tax Planning. Alex decides on a property valued at AED 2 million. They consult an Australian tax advisor who confirms that selling the required amount of ETH will trigger a large CGT event. Alex uses Koinly to aggregate transaction data, calculating a capital gain of AUD $600,000 on the ETH sale. As it was held for over two years, they can apply the 50% CGT discount. They set aside funds to pay this tax liability.
Step 2: Cross-Border Transfer. Alex sells the ETH for USDC on a regulated Australian exchange. The exchange files a report with AUSTRAC. Alex then transfers the ~US$545,000 in USDC to a reputable, licensed crypto exchange in the UAE. The entire transfer takes less than 15 minutes and costs a few dollars in Ethereum gas fees.
Step 3: Property Purchase. Working with a crypto-friendly real estate broker in Dubai, Alex's USDC is converted to AED through the UAE exchange. The funds are then transferred to the developer's escrow account, as required by the Dubai Land Department (DLD). The title deed is registered, and Alex receives their 10-year Golden Visa.
Step 4: Ongoing Compliance. Alex's Australian tax advisor reminds them of their ongoing obligations. If they rent out the Dubai apartment, the net rental income must be reported to the ATO annually. If they sell the property in five years, the capital gain—calculated in AUD—must be declared on their Australian tax return. Even while living in Dubai, as long as they remain an Australian tax resident, their global assets and income are within the ATO's purview. Detailed records of all transactions are maintained.
Frequently Asked Questions
How are crypto-funded property purchases reported to AUSTRAC?+
Australian exchanges must report all fund transfers of any value and physical cash transactions of AUD $10,000 or more to AUSTRAC. This includes crypto-to-fiat conversions used for international property purchases, ensuring compliance with anti-money laundering regulations and providing authorities with transaction visibility.
What are the advantages of using stablecoins for international property purchases?+
USDC stablecoin transfers finalise on-chain in seconds to minutes, compared to 2-5 business days for traditional SWIFT wire transfers. This speed advantage, combined with lower fees and 24/7 availability, makes stablecoins attractive for time-sensitive property transactions and cross-border settlements.
How have recent tax changes affected crypto property investment strategies?+
Portugal's introduction of a 28% tax on crypto gains held for less than one year from January 2023 ended its status as a zero-tax haven. This shift has prompted investors to reconsider their jurisdiction choices and holding periods when planning crypto-funded international property investments.
What are typical Golden Visa investment thresholds for property?+
Residency-by-investment programs often start at €250,000 (approximately AUD $415,000) for real estate investments, with higher tiers available for direct citizenship pathways. These programs attract crypto investors seeking diversification and international mobility through property ownership and residency rights.
How does the ATO track offshore crypto property investments?+
The ATO automatically receives financial account data from over 100 jurisdictions under the Common Reporting Standard (CRS). This increases visibility of offshore assets, including crypto-funded property purchases, requiring Australian investors to properly declare international real estate holdings and associated capital gains.
Recommended Reading
Key Statistics
Dubai Crypto Acceptance
Multiple developers accept Bitcoin and USDT
Portugal Crypto Buyers
Growing market of crypto wealth seeking property
Turkey Crypto Usage
High adoption — AML rules apply to property purchases
Tokenised Real Estate
RealT, Lofty — fractional ownership platforms emerging
ATO CGT Trigger
Using crypto to buy property is a disposal event
Crypto Mortgage
Nexo and similar — collateralised loans without selling BTC