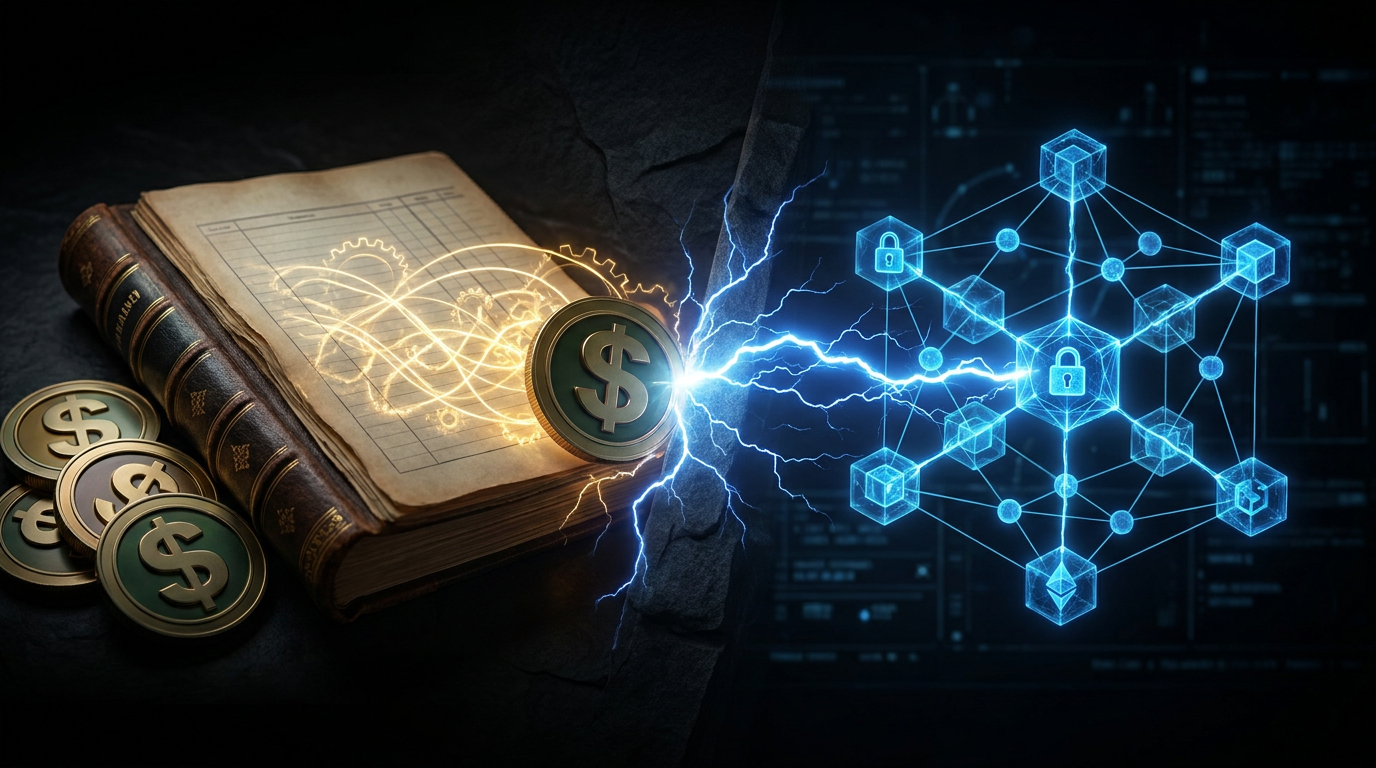
On-Chain Settlement vs Traditional Rails: The Convergence Trade
This article was produced with AI assistance and reviewed for accuracy.
Content is for informational purposes only and does not constitute financial advice.
Two Settlement Models, Two Different Risk Profiles
Traditional payment rails, ACH, SWIFT, and card networks like Visa and Mastercard, rely on a chain of intermediary banks and clearinghouses that each maintain their own ledgers. A wire sent from a US bank to a counterparty in Singapore typically passes through correspondent banks, each reconciling balances before the recipient sees funds. This system works, but it introduces settlement risk, batch-processing delays, and operating hours that don't run on weekends or holidays.
On-chain settlement collapses that chain into a single shared ledger. When a transaction is confirmed on a blockchain like Bitcoin or Ethereum, there is no separate reconciliation step between banks, the ledger update is the settlement. This is why the CFTC has publicly pushed tokenization of traditional assets and why the SEC has signaled openness to onchain stock trading, according to recent coverage of CFTC leadership comments, the appeal isn't ideology, it's operational efficiency at institutional scale.
The tradeoff is finality architecture. Traditional rails offer legal recourse, chargebacks, and regulatory dispute resolution built up over a century of banking law. Blockchain settlement is typically final and irreversible once confirmed, which removes counterparty ambiguity but also removes the safety net of a bank reversing a fraudulent transfer.
Where TradFi Institutions Are Actually Testing This
The convergence isn't theoretical. Austrian bank Raiffeisen recently announced it will offer crypto trading across 11 European markets through a partnership with Bitpanda, a move that brings regulated custody and on-chain asset access directly into a mainstream retail banking relationship rather than routing customers to standalone exchanges. Separately, the European Central Bank's Pontes platform has been described as a signal of wholesale crypto-TradFi convergence, aimed at exploring how central bank money settlement could interact with tokenized markets.
These moves matter more than headline price action. A hedge fund analyst tracking institutional flows would note that when a regulated deposit-taking bank builds crypto access into its core product rather than partnering at arm's length, it's underwriting operational and compliance risk that retail platforms don't carry. That's a different signal than an ETF inflow number.
What This Means for Market Structure
The practical effect of settlement convergence is liquidity fragmentation risk giving way to liquidity consolidation. As tokenized versions of traditional securities settle on the same rails as crypto assets, cross-asset collateral and margin efficiency improve, institutions can move collateral between a tokenized bond position and a crypto derivative without waiting on multi-day settlement cycles. This is the structural argument behind CFTC-driven tokenization pilots. It won't eliminate volatility, but it changes who can participate and how fast capital moves between asset classes. For a broader view of how digital assets stack up against equities and bonds, see Crypto vs Traditional Asset Classes.
Background and Context
For readers newer to the space, understanding how settlement and custody actually work is foundational before evaluating institutional adoption claims. For deeper context, see our guide on How to Buy Crypto in Australia — A Complete Beginner's Guide for 2026, which covers exchange selection, custody, and the basic mechanics retail investors need before engaging with any settlement layer, on-chain or otherwise. The same custody principles, hardware wallets over exchange balances, apply whether you're holding Bitcoin or a tokenized security.
This convergence theme also runs through broader capital markets analysis at WealthWatchPro investment intelligence, which tracks how institutional allocation decisions are shifting alongside these infrastructure changes.
What to Watch
Watch for further central bank pilot disclosures following the ECB's Pontes work, additional bank-crypto partnerships modeled on Raiffeisen's Bitpanda deal, and any formal SEC guidance on tokenized equity trading following the CFTC's public tokenization push. The Fear and Greed Index currently sits at 71, in Greed territory, a reminder that institutional infrastructure build-out and short-term sentiment swings are separate signals worth tracking independently rather than conflating.
The Long Game
Settlement convergence is a multi-year infrastructure story, not a single catalyst. Investors watching this space should track regulatory tokenization pilots and bank partnership announcements as leading indicators, since these operational commitments tend to precede retail-facing product changes by quarters, not days.
Sources & Further Reading
Get CoinHours in your inbox
Crypto markets, cycles and on-chain signals in your inbox.